
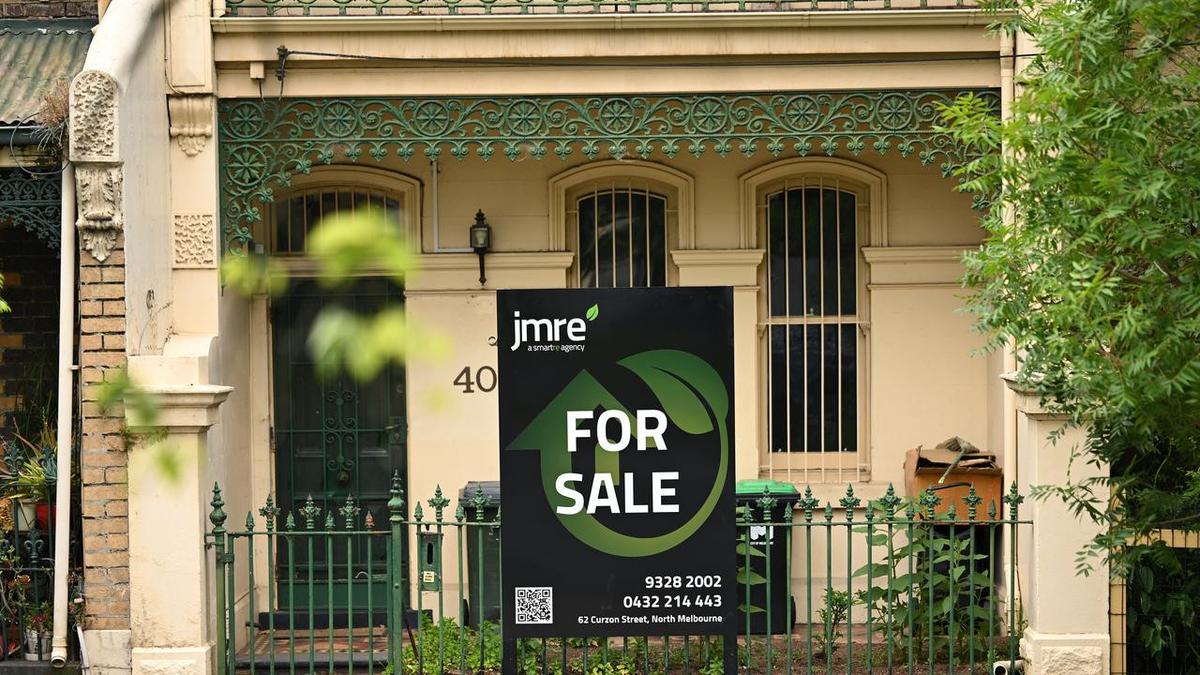
Australian mortgage demand has suffered its sharpest annual decline since 2022, with higher interest rates, strict serviceability tests and rising living costs deterring prospective buyers despite a fall in property prices.
Overall demand dropped 19.2% in September compared with the same month last year, while new home loan applications fell 22.1%, according to credit reporting body Equifax. House prices across Australia slipped 1.1% over the same period.
The downturn has been particularly severe among younger borrowers. Mortgage demand fell by 25% among 18 to 25-year-olds and by 22.5% for those aged between 26 and 35.
Kevin James, chief solution officer at Equifax, said the figures represented the largest year-on-year fall in first home buyer mortgage demand since December 2022.
“This is the largest year-on-year decline in first home buyer mortgage demand since December 2022 and baseline prices for properties remain high despite recent market dips,” he said.
First home buyers face higher barriers
Although property values have eased, the cost of entering the market remains high. The average first home buyer mortgage size has reached about $743,000, according to Equifax.
Mr James said aspiring homeowners were facing several pressures at once, with borrowing assessments, interest rates and household expenses making it harder to secure a loan.
“There is no silver bullet solution, each element needs to be considered when looking for ways to make the market more accessible for this cohort,” he said.
For many prospective buyers, he added, meeting both the deposit requirement and the repayment threshold was becoming increasingly difficult without support from family or financial institutions.
The figures also showed signs of strain among existing borrowers looking to switch lenders. Lender-switching fell 8.8% over the year after remaining almost flat in August.
“Many existing mortgage holders wanting to shop around for a better rate are likely finding themselves unable to clear the serviceability needed, effectively locking them into their current arrangements,” Mr James said.
Credit card demand moved in the opposite direction, rising 10% year-on-year, driven by a 36.3% increase among borrowers aged 56 and over. Demand among 18 to 35-year-olds, however, weakened across the wider credit market.
Equifax said the increase in credit card applications was linked to consumers changing cards ahead of the Reserve Bank’s interchange fee cap reduction taking effect on October 1, and expected that particular source of demand to fade as borrowers settled on suitable rewards terms.
