
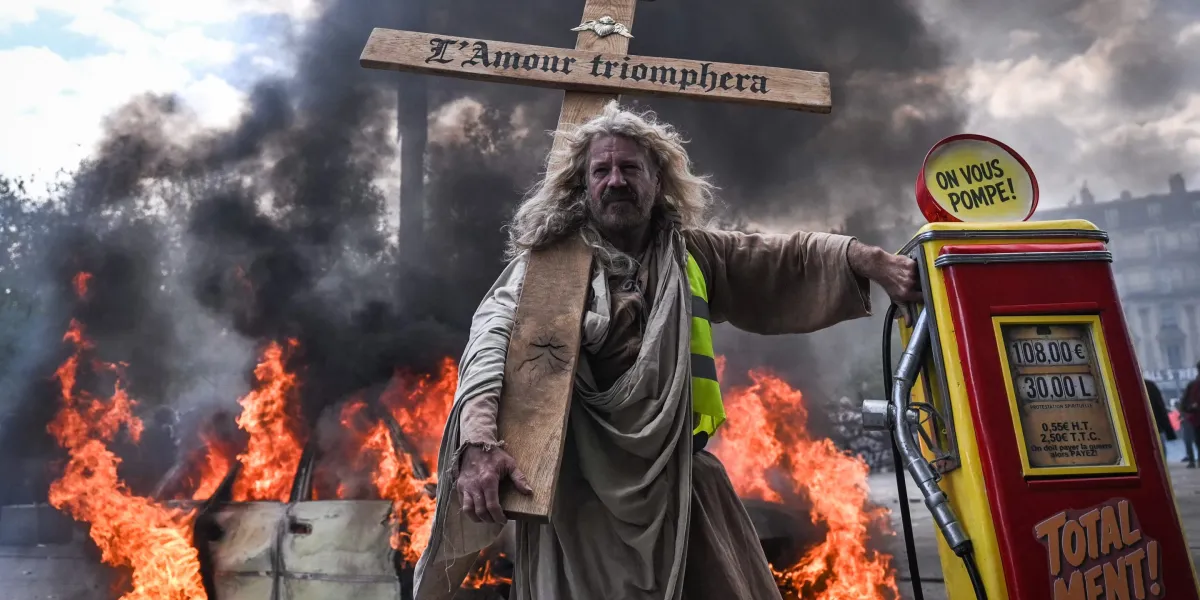
France’s riots have exposed a wider crisis over public services, living costs and government debt, with unrest spreading through major cities as politicians argue over its causes. More than 2,400 people were arrested on Saturday, nearly 1,000 police and gendarmes were injured, and businesses were looted in Paris, Marseille, Lyon and elsewhere.
A fire that badly damaged Limoges’ 19th-century city hall was started deliberately, according to the local prefect. Fires and looting continued on Sunday night, prompting Prime Minister Sébastien Lecornu to order localised curfews.
Interior Minister Laurent Nuñez said police had “lost control” and offered to resign, but President Emmanuel Macron refused to accept it.
The unrest began with protests by school pupils in the Paris suburbs in mid-September. They complained of missing teachers, overcrowded classrooms and buildings unable to cope with high temperatures, while accusing successive governments of years of underinvestment.
Teachers and trade unions later joined the demonstrations, alongside people protesting over fuel prices and the rising cost of living. Student demands have not included immigration or religion.
France riots expose pressure on public services
France’s education system is facing significant staffing and infrastructure problems. The country’s Education Ministry statistics office said 9.8% of teaching hours in public middle and high schools went undelivered during 2024-25, mainly because absent teachers were not replaced.
A survey of 1,033 schools by SNES-FSU, France’s largest secondary teachers’ union, found that 53% of middle and high schools were missing at least one teacher at the start of the current school year. The OECD has estimated that 11.1% of French secondary teachers are not fully qualified.
Similar strains are evident in the United States. The Government Accountability Office found that 19% of US school districts cancelled classes during the same year because of building problems, affecting about two million pupils and costing roughly 3.5 million days of learning.
At the start of the 2024-25 school year, 74% of US public schools reported difficulty filling at least one vacancy with a fully certified teacher. The Learning Policy Institute estimates that 387,843 teachers are not fully certified for their assignments, describing its figure as an undercount.
US President Donald Trump attributed the violence in France to migration. In a Truth Social post on October 6, he described it as “nothing less than out-of-control mass migration” and said it “isn’t about schools, this is about Islam wanting to take over a once great country”.
Paul Donovan, chief economist at UBS Global Wealth Management, described the comments as “a different form of scapegoat economics”.
Debt and growth divide France and the US
Although the United States has higher inflation, its stronger economic growth has provided a degree of protection from the pressures now visible in France. US consumer prices rose 3.7% in the year to September, compared with 3.4% in France on the EU-harmonised measure.
US gross domestic product increased by 2.2% in the second quarter and unemployment stood at 4.2%. France, by contrast, expects growth of only 0.5% this year, while youth unemployment is about 20%.
The two countries share a more troubling similarity in their public finances. French public debt has reached 119% of GDP, while US debt held by the public stood at 100.2% of GDP at the end of March.
Mr Lecornu’s budget, which aims to reduce France’s deficit from 5.4% to 5% of GDP, faces a critical vote in the National Assembly. The US ran a deficit of 1.992 trillion dollars in fiscal 2026, equivalent to about 6.2% of GDP based on Congressional Budget Office projections.
Bond markets have treated the two countries in a similar way. Bank of America economists Claudio Irigoyen and Antonio Gabriel said French and US 10-year yields had been moving along nearly the same path, arguing that both governments had been encouraged to borrow more when interest rates were low.
They warned that when cheap borrowing finances a lasting expansion of the deficit, rising interest rates make the spending cuts needed to restore the public finances politically difficult.
In the United States, the warning has come through the bond market. After Treasury Secretary Scott Bessent told an audience at Southern Methodist University, “I am the house now”, the 30-year Treasury yield climbed as high as 5.69% over the following three weeks, its highest level since 2002.
US growth is also increasingly tied to technology investment, which accounts for about a third of economic expansion, according to ING. Yet a Bentley-Gallup survey found that 39% of Americans believed artificial intelligence did more harm than good, rising from 31% a year earlier, while 79% expected it to reduce US jobs over the next decade.
The immediate political pressure remains greater in France, where weak growth, strained public services and proposed deficit reductions have combined to fuel unrest. But the similarities with the United States suggest that the underlying risks are not confined to one country.
As economist Rüdiger Dornbusch put it: “Crises take longer to arrive than you can possibly imagine, but when they do come, they happen faster than you can possibly imagine.”
