
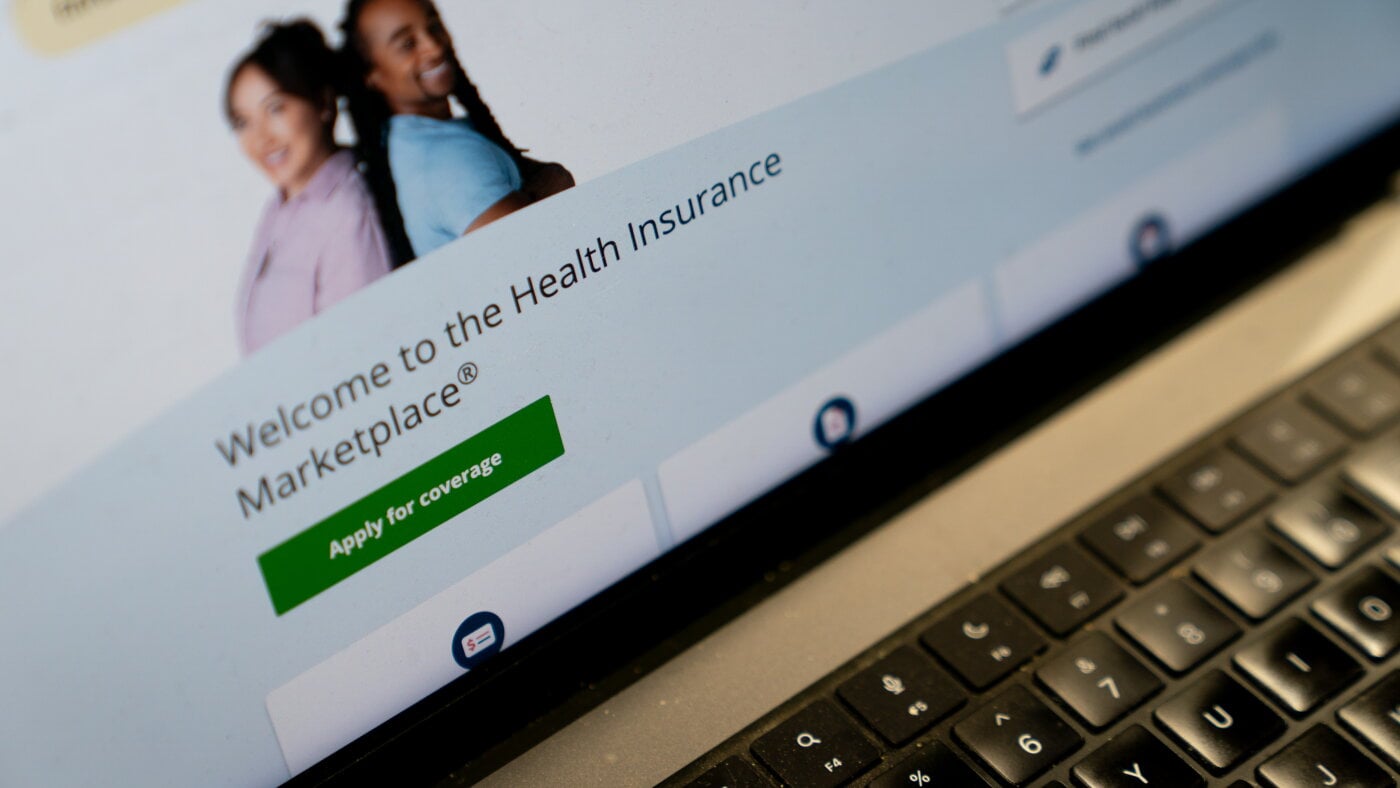
The Trump administration’s cancellation of 760,000 Affordable Care Act health insurance enrolments over alleged fraud has wrongly removed some legitimate policyholders, insurance industry sources have said, with a small number already reinstated.
Officials announced the cuts last month while claiming they would prevent improper enrolments and save taxpayers billions of dollars. But the administration has provided little information about how many cancellations were reversed, how people were contacted or how quickly wrongly removed customers can regain cover.
A further 419,000 enrolments are now being reviewed. Insurers are expected to tell the Centers for Medicare and Medicaid Services (CMS) how many of those customers failed to respond to contact attempts around mid-to-late November, after the US midterm elections.
David Merritt, senior vice-president of external affairs at the Blue Cross Blue Shield Association, confirmed that some of the group’s members had been reinstated. He said CMS had an expedited review process for people who discovered that their cover had been cancelled incorrectly.
How the Affordable Care Act cancellations were made
CMS identified almost 1.2 million accounts for further examination after finding four warning signs it associated with possible fraud: no Social Security or immigration document number, involvement by a broker, no monthly premium payment and no contact with the insurer or claims filed.
The agency then sent lists of accounts to insurers, which were told to use at least two forms of contact, such as a telephone call and a letter. Policyholders were given 30 days to respond and provide missing information before CMS cancelled their cover.
Critics argue that the process could have caught people who were legitimately enrolled but failed to open a letter, answer an unfamiliar telephone number or complete paperwork in time. A lack of claims, for example, does not necessarily indicate fraud because some people do not see a doctor or visit hospital during a year.
Katie Keith, a director at Georgetown Law’s Center for Health Policy and the Law, said: “It may be true that some of those enrollments were not authorized, but it can be equally true that people got lost in the shuffle and have a valid enrollment. Without more information, it’s almost impossible to tell.”
She added: “That they are not being very transparent is telling too.”
Agents have been helping insurers reach people named in the review. Johnny Wallin, chief operating officer of Texas-based Marketplace Insurance Exchange, said his organisation had mounted an “all-hands-on-deck” effort to contact customers, including some who were abroad.
His agents were unable to reach about 60 people. In another case, they helped a customer upload a new green card after a language barrier and an expired document had complicated the process.
Oscar Health was among the insurers involved in the review. In a regulatory filing, the company estimated that between 250,000 and 300,000 of its members could lose cover as a result of the CMS action, although its chief executive said the company had made contact with a number of people on the agency’s list.
The administration has also removed subsidies from about 189,000 ACA policyholders who had duplicate Medicare, Medicaid or Children’s Health Insurance Programme coverage. Officials said those cases reflected concurrent cover or continued coverage for people who had died, rather than fraud.
Supporters of the crackdown, including Brian Blase of the Paragon Health Institute, say most of the 760,000 cancellations involved people who had been signed up without their knowledge by rogue call centres, or accounts belonging to people who did not exist. That remains contested by policy experts and insurance representatives.
Matthew Fiedler, a senior fellow at the Brookings Institution, said: “There will be legitimate people who don’t have a claim or don’t respond to an inquiry from an insurer.” He added that the process was preferable to cancelling people at random, but was “likely to miss the mark”.
The cancellations affect only the states using the federal Healthcare.gov marketplace. Many of those states, including Texas, Florida, Louisiana and Mississippi, saw rapid growth in ACA enrolment between 2020 and 2025, partly because of enhanced subsidies introduced during Joe Biden’s presidency that have since expired.
Overall ACA enrolment has fallen by nearly three million in the first months of the year. The administration has attributed part of the decline to its efforts to remove improper enrolments and to changes including the abolition of a special year-round enrolment period for people on low incomes.
CMS has suspended some brokers over alleged improper activity and barred new brokers from enrolling customers through the federal exchange during the next open-enrolment period. The agency said it had no additional data to release on the reasons for the cancellations.
Ronnell Nolan, president and chief executive of the Health Agents for America trade group, said the industry supported action against fraud but did not want healthy customers who simply had not needed medical treatment to lose their insurance.
