
US debt interest payments reached a record share of the economy in fiscal 2026 as the federal deficit widened to $1.99 trillion, intensifying concerns over the sustainability of America’s borrowing.
Treasury data showed the deficit was 12% higher than the $1.78 trillion gap recorded in fiscal 2025. Spending rose 6% to $7.4 trillion, while revenue increased by 3% to $5.4 trillion.
Interest on the national debt was the third-largest federal spending category, behind Social Security and Medicare but ahead of defence and Medicaid.
US debt interest payments rise as borrowing costs increase
Gross interest costs reached $1.36 trillion during the year, with the average interest rate rising to 3.53%. That was more than twice the rate recorded in 2021, before the Federal Reserve began an aggressive campaign of interest-rate rises to curb inflation.
Net interest payments climbed 8% to $1.05 trillion, increasing faster than overall spending, revenue and economic output. The figure was equivalent to about $2.9 billion a day and represented 3.2% of GDP, according to the Peter G Peterson Foundation.
That surpassed the previous record, set in 1991. Gross US debt now stands at $40 trillion, while publicly held debt is equivalent to 100% of GDP.
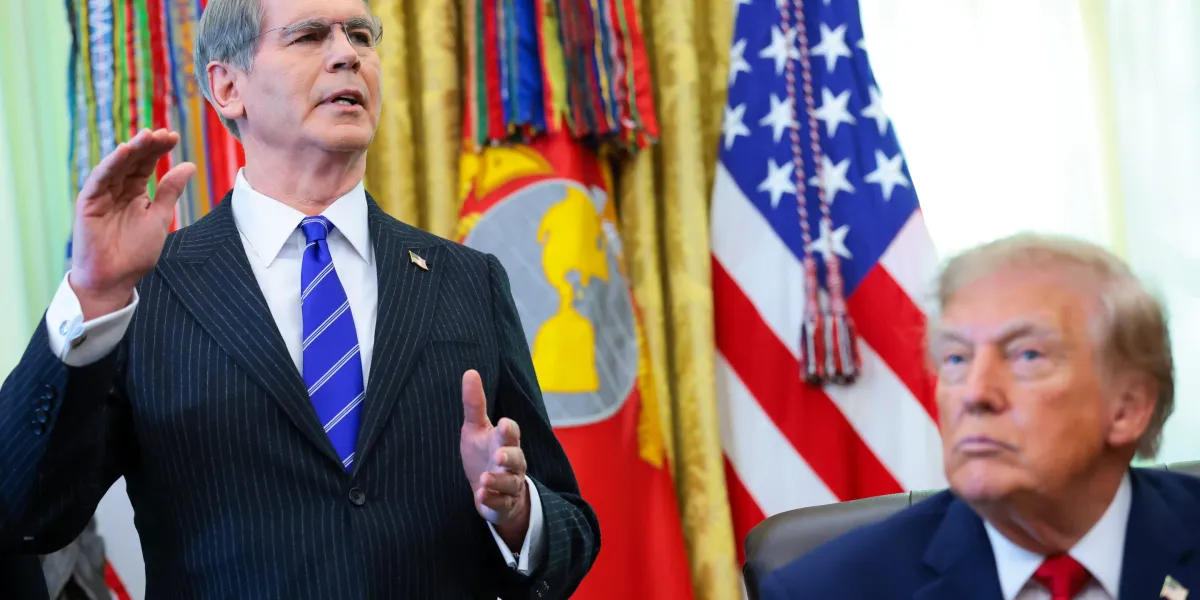
The debt burden is also increasingly exposed to movements in financial markets. Treasury Secretary Scott Bessent has been issuing more short-term debt to finance the deficit while retiring longer-term obligations.
More than $10 trillion, or about one-third of publicly held debt, is due to mature within the next 12 months. That means the government will have to refinance a substantial share of its borrowing at current, higher rates.
The Congressional Budget Office projected in February that annual interest costs would reach $2.1 trillion by 2036. But Treasury yields have since risen sharply after the Iran war launched by President Donald Trump sent oil prices and bond yields higher.
The yield on the 10-year Treasury bond is now above 5%, exceeding the CBO’s forecasts of 4.1% this year, 4.2% in 2027 and between 4.3% and 4.4% in subsequent years through 2036.
The Committee for a Responsible Federal Budget estimates that if yields remain about one percentage point above the CBO’s projections, interest costs could reach $2.8 trillion by the end of the decade, equivalent to 5.9% of GDP.
“Higher interest begets more debt, and greater debt begets higher rates and higher interest. Eventually, the whole thing could come crashing down,” Maya MacGuineas, the committee’s president, said last month.
She added: “That’s why Washington needs a fiscal intervention now, before it’s too late. The President, the Treasury Secretary, and Congressional leadership need to understand the severity of this issue. There are no easy fixes, and we can’t just wish this problem away.”
There has so far been little sign of political willingness to reduce spending or increase revenue. Mr Trump has called for a $5,000 “dividend” payment to Americans if Republicans win the midterm elections and is distributing “rebates” to millions of Medicare and Affordable Care Act enrollees.
Mr Bessent has argued that stronger economic growth could help bring the debt under control. “With 3% growth, we grow our way out of this,” he said at Southern Methodist University last month.
However, Phillip Swagel, the CBO director, said faster growth was unlikely to stabilise the debt on its own. While a stronger economy would increase government revenue, it could also push up wages, Social Security spending and interest rates.
Mr Swagel estimated that, with interest rates between 4% and 5%, nominal GDP growth would need to reach 7% to 8%, while real growth would have to rise to 5% to 6% to stabilise the debt.
Real GDP grew at an annual pace of 2.2% in the second quarter, while even the most optimistic Wall Street forecasts put full-year growth at 2.5%.
“So growth will help, but it’s probably not plausible that growth alone will stabilise our fiscal trajectory,” Mr Swagel said. “So then we’re left with changes in revenues and changes in spending, and those are political choices.”
