
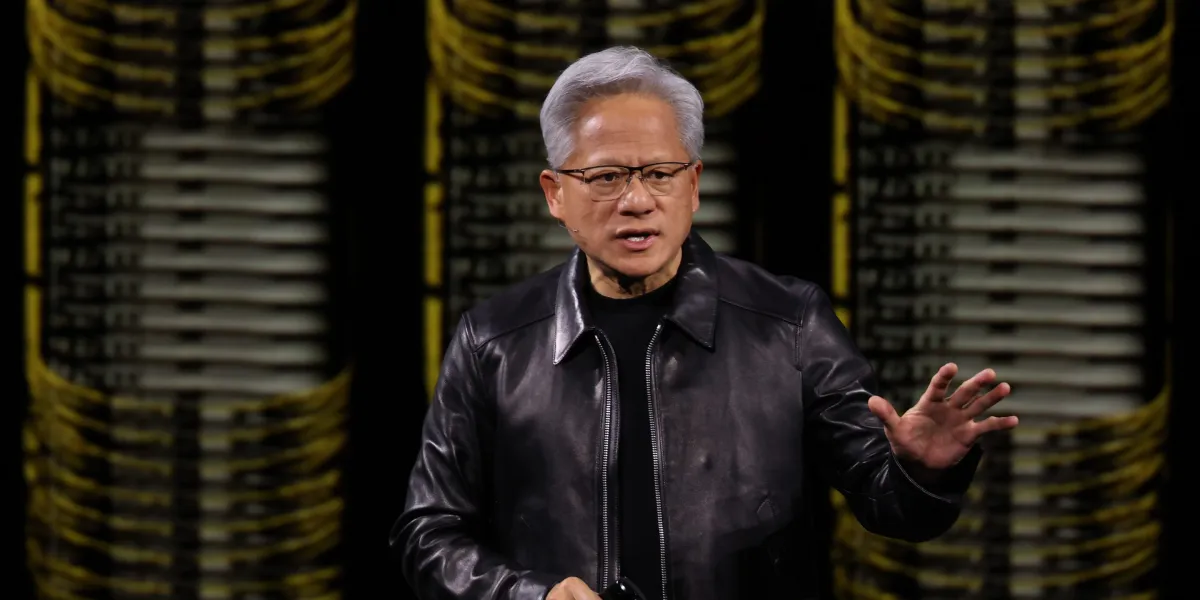
Nvidia’s governance crisis has intensified after strong earnings led interim chief executive Colette Kress to raise forecasts, while new board chair Harvey Jones appeared to rule out Jensen Huang’s return amid investigations involving the former chief executive and the company.
Kress was praised for leading the earnings call with confidence and candour, reinforcing the argument that Nvidia’s performance is not dependent on a single figure. The results were presented as evidence that the semiconductor company can continue to grow without Huang at the helm.
Huang has nevertheless indicated that he would be willing to return. “If the Board of Directors decides that my return is in the best interest of our shareholders, our employees, the company, and America, I would be honored to answer these calls and return as CEO,” he said.
His comments came as the Securities and Exchange Commission was reported to be examining Huang and Nvidia. The former chief executive is also described as being the subject of four ongoing government investigations, including congressional oversight hearings and federal probes, as well as shareholder lawsuits.
The dispute has divided opinion between supporters calling for Huang to return and governance specialists arguing that Nvidia’s board failed to exercise proper oversight. The central criticism is that the company’s problems stemmed less from its formal structure than from the judgement and character of its leadership, and from a board that failed to challenge it effectively.
Nvidia governance crisis exposes limits of board checklists
Some technology executives and investors have criticised the board’s actions and attacked what they regard as overly cautious management practices. Telegram founder Pavel Durov summarised that view in a post on X: “Jensen made a rookie mistake. He had a board.”
Critics of that position argue that executives entrusted with shareholders’ money owe a fiduciary duty to investors and cannot accept the benefits of corporate control while rejecting accountability.
Governance commentators, meanwhile, have pointed to measures including the separation of the chair and chief executive roles, independent directors and voting arrangements. But Nvidia already had a single-class share structure rather than dual-class shares, and had an independent lead director, Stephen Neal, the former chief executive of Cooley Law Firm.
Before Huang’s departure, the company also had independent audit, compensation and governance committees, annual elections for directors and a one-share, one-vote structure. Every director other than Huang was technically independent, and shareholders re-elected the entire ten-member board in June, with Huang receiving 99 per cent support.
The commentary argues that those features demonstrate the weakness of relying on governance scorecards. A board can meet formal standards while still failing to identify serious risks or challenge a dominant chief executive.
Examples cited include Enron, whose board had 12 independent directors out of 14 and separated the chair and chief executive roles in its final year, as well as Silicon Valley Bank and Lehman Brothers, both of which had largely independent boards. Stanford researchers are also said to have found no significant correlation between a major governance rating and measures including financial restatements, shareholder lawsuits and share performance.
The argument is not that board structures are irrelevant, but that independence, committee composition and voting rights cannot substitute for judgement, courage and effective relationships between directors and management.
Questions over board expertise and succession planning
The most serious concerns raised about Nvidia relate to the calibre and experience of its directors. None of the company’s directors had previously run an S&P 500 company, and none had national security experience, despite the importance of Nvidia’s chips to national security.
Microsoft, IBM and Dell were cited as companies with at least four current or former large-company chief executives on their boards. Nvidia, by contrast, had no such directors.
The board was also accused of failing to prepare a credible succession plan. Huang had more than 60 direct reports and no president or chief operating officer beneath him, while the company’s approach to business was described as relying on handshake agreements and concentrating authority in the chief executive.
When the crisis emerged, the board’s initial response was reportedly to defend Huang before its own investigation had been completed. That response later changed as concerns about his conduct and the company’s affairs became more difficult to dismiss.
The company’s reliance on outside advisers has also been questioned. PwC signed off Nvidia’s financial reports, but critics have alleged that the accounts obscured the geographical origins of revenue and the end users of sensitive chips. Those claims remain allegations and could expose the board to legal scrutiny if they were substantiated.
The wider lesson offered by the Nvidia case is that directors cannot delegate their core responsibilities to accountants, lawyers or proxy advisers. Professional advice may inform a board’s decisions, but responsibility for oversight remains with the directors themselves.
How boards should handle powerful founders
The dispute has revived a longstanding question about how boards should work with larger-than-life founders. The suggested approach is neither unquestioning loyalty nor an automatic confrontation, but a relationship in which directors retain the founder’s creative strengths while placing limits on excessive power.
Boards at Microsoft, Amazon, Dell, Starbucks and Apple were cited as examples of companies that found ways to work with influential founders and chief executives including Bill Gates, Jeff Bezos, Michael Dell, Howard Schultz and Steve Jobs.
That balance requires directors to create an environment in which management can disclose bad news early, dissent is expected and authority can be challenged. It also requires directors to assess their own performance as rigorously as they assess the chief executive’s.
For Nvidia, the key issue was therefore not whether its shares were single-class or dual-class, or whether it met the technical tests promoted by governance advisers. It was whether the board had the independence, experience and resolve to question Huang, plan for his succession and respond appropriately when concerns arose.
Huang’s supporters continue to argue that shareholders would benefit from his return. But the company’s latest results and Kress’s handling of the earnings call have strengthened the case that Nvidia can operate successfully without him, while the investigations and unresolved governance questions make any comeback more contentious.
