
Faster economic growth is unlikely to stabilise the US debt burden on its own, the director of the Congressional Budget Office has warned, with debt held by the public already equal to 100% of GDP.
Phillip Swagel said the US economy would need an exceptionally strong and sustained expansion even to keep the debt-to-GDP ratio from rising. The CBO currently expects the ratio to reach 120% by 2036.
Speaking at a Minneapolis Federal Reserve conference, Mr Swagel said stronger growth would increase government revenues but would also bring higher spending and potentially more costly borrowing.
Federal spending can itself support economic activity, he said, lifting wages and influencing Social Security outlays. A stronger economy may also push interest rates higher, increasing the cost of servicing the debt.
“So growth will help, but it’s probably not plausible that growth alone will stabilize our fiscal trajectory,” Mr Swagel said. “So then we’re left with changes in revenues and changes in spending, and those are inherently political choices.”
The comments came after Minneapolis Fed president Neel Kashkari asked whether artificial intelligence could generate the growth needed to improve the fiscal position.
Mr Swagel said the CBO had detected an increase in total factor productivity, a measure of how efficiently labour, capital and other inputs are used. Its next economic forecasts, due early next year, will include its assessment of AI, and he said future growth was likely to be stronger.
Even so, he cautioned that AI-driven expansion would not be sufficient to overcome the scale of the budget deficit. In rough calculations, assuming interest rates of 4% to 5%, he estimated that nominal GDP growth would need to reach 7% to 8%, while real growth would have to rise to 5% to 6%, to stabilise the debt.
That would be more than twice the latest real GDP growth rate of 2.2% recorded in the second quarter. Even the more optimistic Wall Street forecasts cited in the discussion put full-year growth at 2.5%.
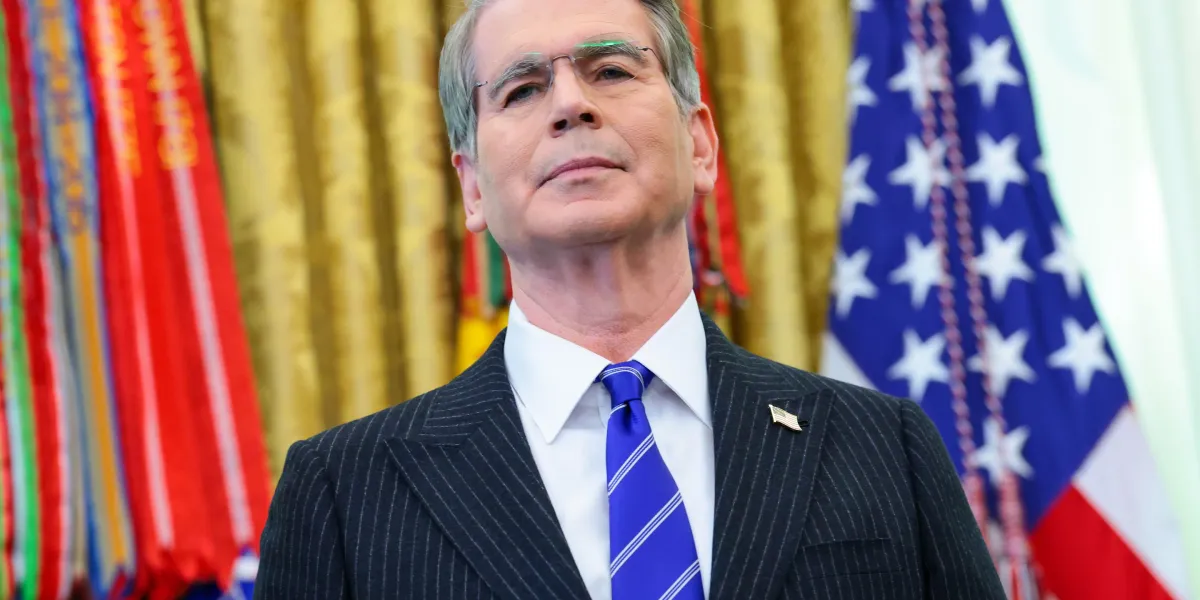
The estimate was also considerably higher than the growth rate suggested by Treasury Secretary Scott Bessent. Speaking at Southern Methodist University last month, he said: “With 3% growth, we grow our way out of this.”
Other projections fall between the two positions. The Penn Wharton Budget Model estimates that growth would need to average 3.5% to 4% over a decade to keep the debt-to-GDP ratio steady.
Mr Swagel also warned that a sudden rise in interest rates could create a damaging feedback loop, as higher borrowing costs widened the deficit and increased debt, putting further pressure on rates.
“So there’s almost like a turbocharger,” he said. “An interest rate shock feeds into the deficit, feeds into the debt, feeds back into interest rates.”
The bond market has so far absorbed the Treasury’s borrowing to fund the deficit, but long-term yields have climbed to their highest levels in 24 years. The increase has also been linked to the strength of the economy, expectations of Federal Reserve rate rises, high oil prices and borrowing by large AI technology companies.
Mr Swagel said the immediate effect of rising debt on long-term rates was relatively small, with a one percentage-point increase in the debt ratio associated with a 0.015 percentage-point rise in long-term interest rates.
“So it’s modest, but the fiscal trajectory is really quite challenging,” he said. “It adds up, and of course there’s that turbocharger type effect that I mentioned where it feeds back into deficits.”
