
Global bond market turmoil eased on Tuesday, giving shares some breathing space as oil prices fell and government bond yields retreated. But France remains at the centre of the market strain, with its 10-year borrowing costs rising more sharply than those of any other country tracked in a recent analysis.
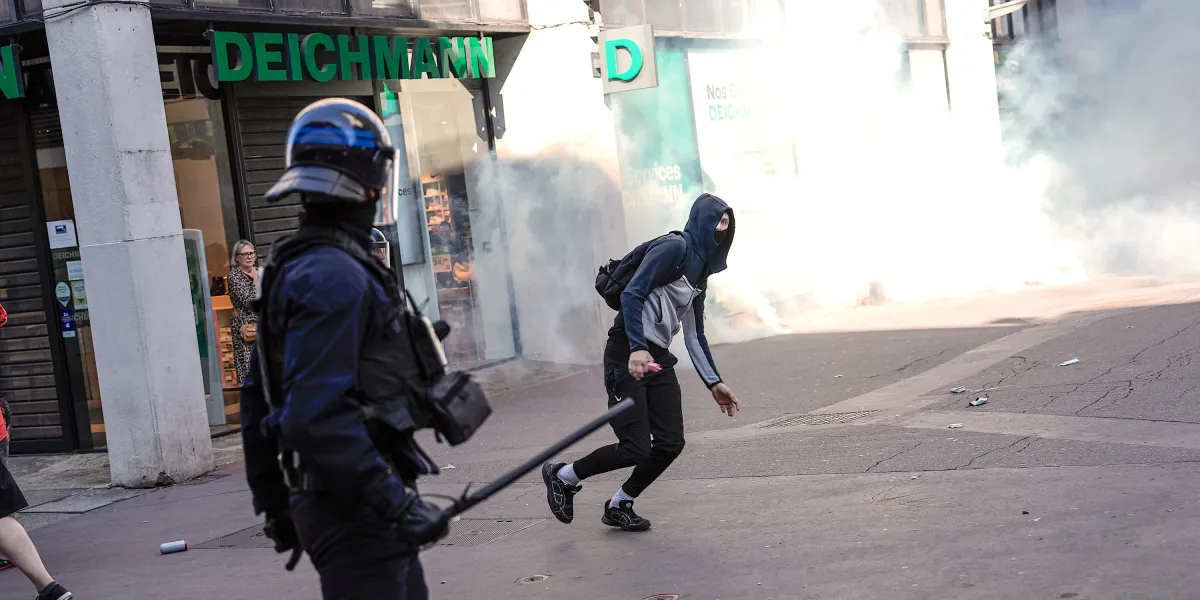
The yield on the 10-year US Treasury fell below 5.3% to 5.27%, while Brent crude dropped to about 98 dollars a barrel. French government bonds also recovered, despite unrest over pressure on public finances and spending on schools.
Jim Reid, of Deutsche Bank, said investors had been dealing with “European contagion risk and a fresh Treasury selloff”. However, he said there were early indications that pressure on France was stabilising, with French debt outperforming.
The improvement in bond markets was reflected in equities. Futures for the S&P 500 rose 0.26% after the index gained 0.66% in the previous session. In Europe, the Stoxx 600 was up 0.94% in early trading and the FTSE 100 had risen 0.86% before lunch.
Japan’s Nikkei 225 gained 1.05% and India’s Nifty 50 rose 0.63%, while South Korea’s KOSPI fell 0.89%. Bitcoin stood at 85,986 dollars.
France bears the brunt of bond market crisis
Data from Yardeni Research showed that yields on 10-year bonds in six of 22 markets had risen by at least one percentage point this year. France recorded the biggest increase, at 131 basis points, followed by the US at 112 basis points.
Italy, Indonesia, Japan and South Korea were also among the countries in that group. The move has left French and US government bonds performing worse than those of Italy and Greece, an unusual reversal highlighted in the analysis.
Higher yields raise the cost of borrowing for governments, companies and households. They can also make government debt more attractive compared with shares, forcing equities to offer a greater potential return to compensate investors for taking on additional risk.
Charu Chanana, chief investment strategist at Saxo, said the apparent resilience of the S&P 500 masked a more uneven performance. The index has risen 13.56% this year, but over the past month only technology and communication services have recorded gains, she said, while all other sectors have fallen.
“There are two simple ways higher yields can hurt equities,” Ms Chanana said. “First, bonds become more attractive. If investors can earn more than 5% from U.S. government debt, stocks need to offer a more compelling return to justify the additional risk. Second, borrowing becomes more expensive.”
The impact is already visible in the US housing market. Mortgage rates, which track longer-term bond yields, have reached about 7.3%, while applications have fallen 6% in a week and 37% compared with the same point last year, according to Christopher Wood of Jefferies.
Some investors argue that a bond market crisis could ultimately force governments to address their finances. Inigo Fraser Jenkins of AllianceBernstein said: “We take the unpopular stance that a bond-market crisis would be a good thing.”
He described such an event as “probably the sole route to engender change and avoid worse intergenerational tension later”, while warning that politicians could try to prevent yields rising, potentially creating inflation and currency problems.
