
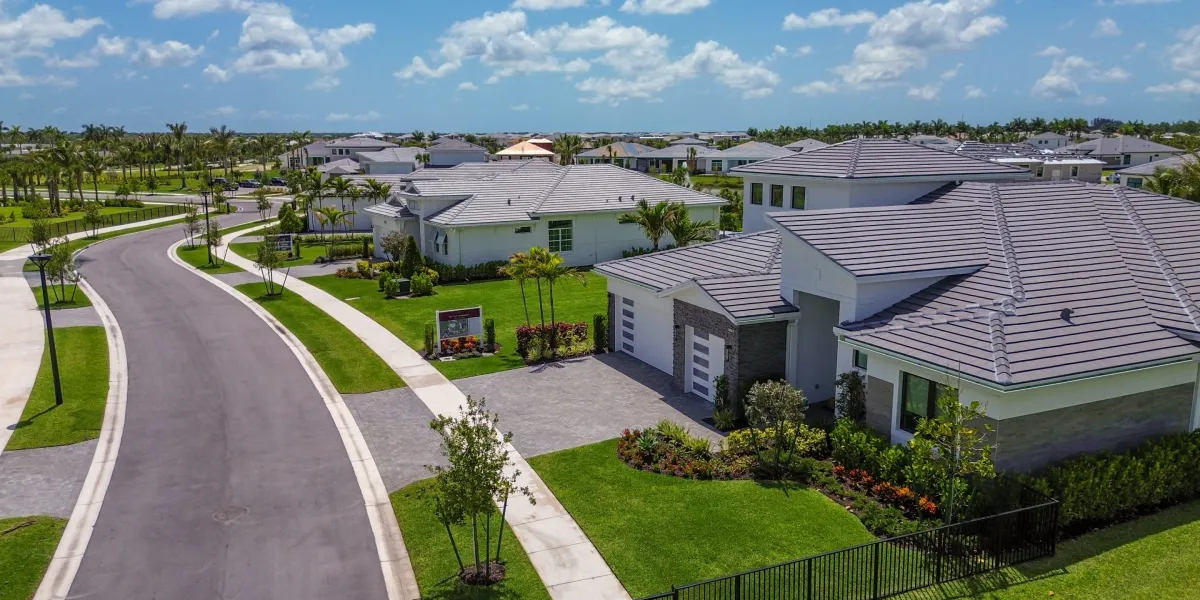
Stocks have significantly outperformed US homes over the past decade, prompting economists to question the long-held assumption that buying property is always the best route to building wealth.
The Case-Shiller Index of home prices rose 87% between December 2015 and December 2025. Over the same period, the S&P 500 climbed 235%, excluding dividends, as the technology and artificial intelligence boom helped drive a run of double-digit annual gains.
The gap has continued to widen in 2026. Nationwide home prices have increased by 1.5%, according to the latest Case-Shiller figures, while the S&P 500 is up 13%, despite sharp market swings linked to the Iran war and concerns about a possible AI downturn.
At the same time, the US housing market has remained largely frozen since the pandemic-era boom ended in 2022. Average 30-year fixed mortgage rates have risen above 7% after aggressive interest-rate increases by the Federal Reserve to tackle inflation.
Those conditions have left many younger Americans unable to enter the housing market. Rather than saving for a deposit on a home they may not be able to afford, some are choosing to rent and invest in shares instead.
Ray Fisman, an economist at Boston University, and Michael Luca, an economist at Carnegie Mellon University, said the contrasting performance should prompt Americans to reconsider how they view homeownership.
“The rent-versus-buy decision involves real trade-offs that too often go unrecognized, especially by those who can comfortably afford to buy,” they wrote in a recent Wall Street Journal op-ed. “Buying a home also bundles two very important, but very different, decisions: where to live, and how to invest a large chunk of your life savings.”
The economists acknowledged that comparing house prices with shares is not a direct like-for-like exercise. A property provides somewhere to live as well as a potential investment return, and the US tax system offers benefits to homeowners.
However, they said strong house-price growth did not necessarily translate into attractive investment returns. Borrowing can also make gains appear larger because buyers typically finance most of a property’s value while contributing only a relatively small amount of equity.
A 20% deposit on a home that rises by 10% in value represents a 50% return on the buyer’s original equity, they noted. But a fall in prices can have an equally powerful effect, particularly because a home is a single, illiquid and undiversified asset.
Fisman and Luca said they were not arguing that people should never buy a home. Ownership can allow residents to remodel without a landlord’s permission, while renting can involve limited supply and the risk of being forced to move.
“Where you want to live need not be where you want to invest,” they wrote, warning against treating the decision about housing and the decision about investment as the same choice.
US home sellers offer concessions as buyers gain leverage
For people primarily deciding where to live, conditions have recently shifted in favour of buyers. Sellers offered concessions in 44.7% of home sales in August, according to Redfin, an increase of 2.1 percentage points from a year earlier and the highest share recorded for that month since at least 2020.
The incentives include mortgage-rate reductions, payments towards repairs and household appliances. Some sellers are offering concessions worth between $10,000 and $20,000 as buyers become more selective.
In some cases, sellers have cut asking prices or offered unusual incentives. One Atlanta estate agent offered a buyer a free week-long holiday at an Airbnb owned by the seller, while an agent in Charlotte offered an all-expenses-paid cruise.
“If we were to quantify all these concessions… we would see that home prices are down, and people are getting better deals,” said Daryl Fairweather, Redfin’s chief economist.
