
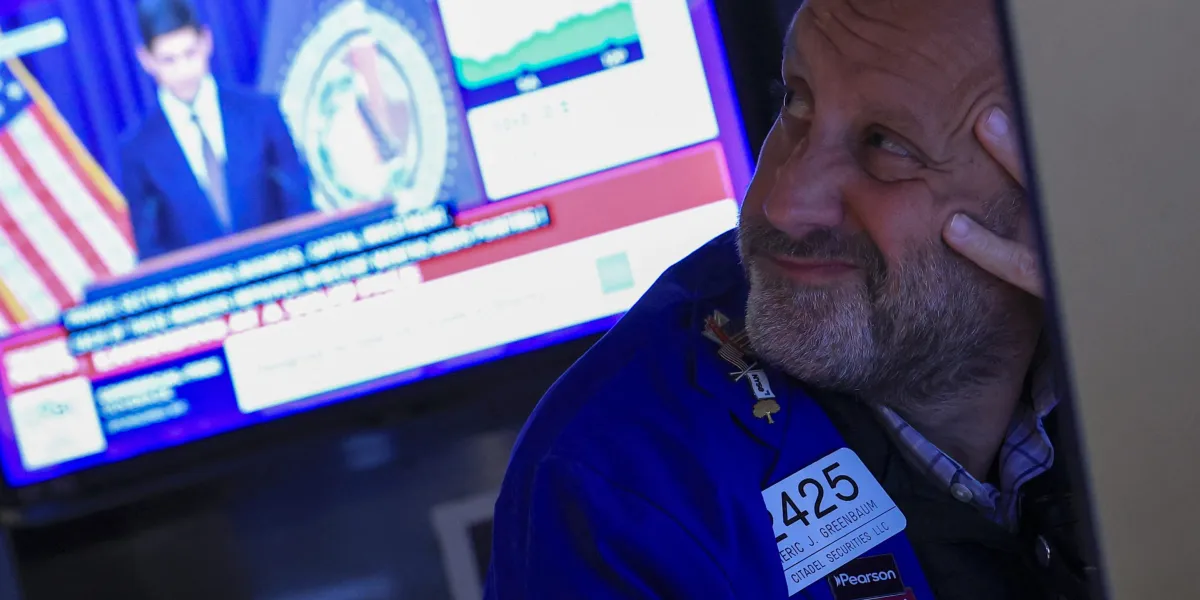
US Treasury yields have climbed to their highest level since 2007, sending borrowing costs higher and leaving investors divided over whether the move reflects a resilient economy or growing concern about America’s debt.
The 10-year Treasury yield reached 5.21% on Friday. The average 30-year mortgage rate rose to 7.45%, while higher government borrowing costs are also expected to feed through to car loans, credit cards and business finance.
The increase came after the Federal Reserve raised interest rates last week for the first time since 2023. Financial markets are pricing in roughly a 70% chance of another increase in October.
Bond prices continued to fall, while demand at a five-year Treasury auction on Wednesday was the weakest since 2018.
Why the 10-year Treasury yield matters
Treasury bonds are effectively loans to the US government. Investors provide the money and receive interest, with the yield changing according to demand. If fewer investors want to lend, the government generally has to offer a higher return to attract buyers.
The 10-year yield is closely watched because it influences the cost of mortgages, car finance, credit cards and business loans. It also affects the appeal of shares: when a relatively low-risk government bond offers a return of about 5%, investors may demand greater potential rewards before buying riskier equities.
Longer-term Treasury yields reflect expectations for Federal Reserve policy as well as a premium demanded by investors for committing their money for a decade. That additional return is intended to compensate for risks including a surge in inflation, a larger deficit, war or another pandemic.
The key question is what is driving the latest rise. If investors expect interest rates to remain high because economic growth is strong, companies could continue to generate robust profits. But if the increase is being driven by a rising term premium, it would suggest investors want more compensation for holding US debt.
Investors split over boom or bust
Optimists argue that the higher yields are a sign of economic strength, with artificial intelligence investment helping to drive growth. Goldman Sachs estimates that the largest technology companies are on course to spend almost $800 billion on capital projects this year and more than $1.1 trillion in 2027.
That would represent the biggest technology investment cycle relative to the size of the economy since the railways, according to the investment bank. A strong economy can also push prices higher, encouraging the Federal Reserve to keep interest rates elevated to contain inflation.
Matthew Klein, an economics commentator who writes The Overshoot blog, said the central bank was beginning to raise rates for the right reason: the economy had remained strong for years and the Fed was becoming more positive about growth and employment.
Jefferies analysts have similarly argued that US companies can withstand higher long-term interest rates, pointing to broad earnings growth.
More pessimistic investors fear that the term premium is rising because of risks beyond the Federal Reserve’s control. They point to Washington’s failure to curb the deficit and the war with Iran, which is approaching its eighth month, as factors that are increasing the supply of Treasury debt.
Artificial intelligence investment could add to the pressure. The spending by major technology companies has outgrown their available cash, meaning they are issuing bonds that compete with Treasuries for investors in an economy where household saving is relatively limited.
Wizman said yields would “stay lofty” without a pause in artificial intelligence spending or the war with Iran, leaving markets to weigh the benefits of a powerful economy against the risks of heavier borrowing and weaker demand for US government debt.
