
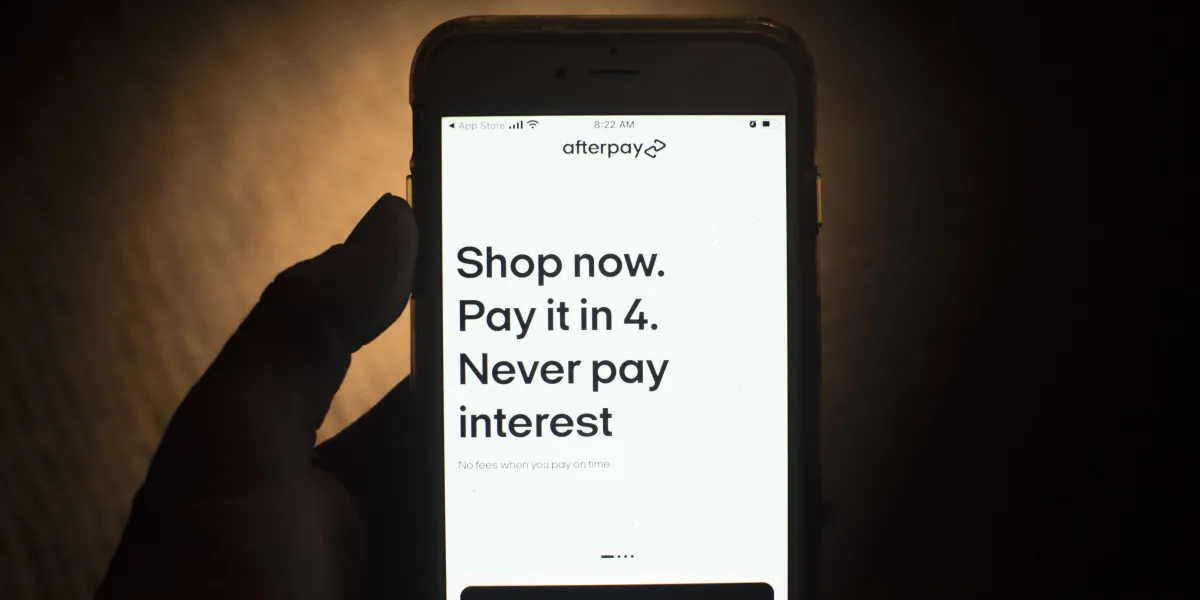
Buy now, pay later financing is being extended from discretionary purchases to rent, highlighting what an analysis describes as the collapse of the financial margin available to middle-class households in the United States.
The development comes as the Federal Reserve has raised its federal funds target range by 25 basis points to between 3.75% and 4%. The 10-year Treasury yield has also risen above 5%.
The central bank has pointed to resilient consumer spending, strong productivity growth and robust capital investment as evidence that economic activity is expanding at a solid pace. But the analysis argues that this strength conceals two sharply different household balance sheets.
Two economies behind the spending figures
The wealthiest 20% of US households now account for about 60% of consumer spending, while the middle-class wage-price margin is described as having fallen 115% from its prewar baseline and turned negative.
Workers are also receiving a smaller share of the value generated by the economy. Labour’s share of non-farm business output fell to 52.8% in the second quarter, the lowest level on record, according to the figures cited in the analysis.
Household wealth increased by a record $12.8 trillion in the same quarter, including $10.7 trillion in equity gains. However, more than 87% of equities are held by the wealthiest 10% of households, leaving those who already owned most of the market best placed to benefit.
The result is an economy in which gross domestic product and overall spending can remain resilient while financial security becomes increasingly concentrated among a smaller group of households.
Higher rates affect households differently
Interest-rate rises do not have the same effect on every household. People with substantial savings and investments may receive higher returns on cash and newly issued fixed-income assets, while those already running at a deficit face increased costs on credit cards, car finance and other borrowing.
Federal Reserve researchers estimate that major buy now, pay later providers originated nearly $160 billion in credit last year. The proportion of users employing the services to finance groceries has doubled in two years, with some households borrowing to pay for essentials such as milk and eggs.
The spread of instalment finance into everyday spending, including housing, suggests that some consumers are no longer using it mainly for optional purchases. Instead, it is becoming a way of managing basic living costs.
Consumer spending accounts for more than two-thirds of the US economy, making the divide a potential weakness. If households with negative margins lose further purchasing power, the effects could move through lower consumption, reduced business revenue and weaker growth.
Expanding the productive economy
The analysis argues that higher borrowing costs cannot resolve a structural imbalance by placing further pressure on households already struggling to meet everyday expenses. It says policymakers should instead focus on expanding the economy’s productive base.
Increasing workforce participation and removing barriers that limit people’s contribution to the labour market are presented as a potential $3.1 trillion economic opportunity in the United States.
A larger productive economy, the analysis argues, could support growth without creating demand-driven inflation and help restore the financial margin of middle-class households, reducing the need to use instalment finance for essentials.
The Federal Reserve has a single interest rate for the economy, but its effects are divided between households that can benefit from higher returns and those borrowing to cover housing and food. The analysis concludes that lasting resilience will require policies capable of addressing both realities.
