
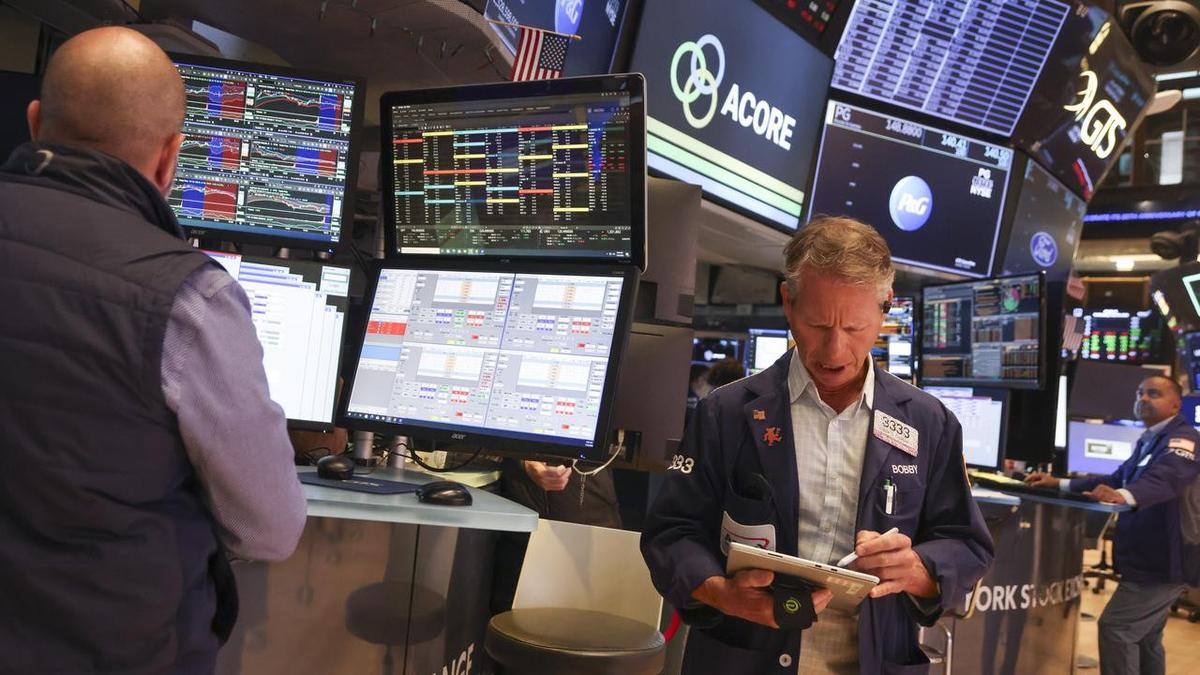
US stock index futures were broadly flat on Tuesday as technology and artificial intelligence shares edged higher, while rising oil prices and elevated government bond yields limited appetite for risk amid a lack of progress in peace talks between the US and Iran.
Dow E-minis were down 37 points, or 0.07%, while S&P 500 E-minis fell 2.75 points, or 0.04%, at 5.06am ET. Nasdaq 100 E-minis rose 18.75 points, or 0.06%.
Chipmakers recovered modestly after a sector-wide sell-off in the previous session. Marvell Technology, Micron Technology and Broadcom each gained about 1% in pre-market trading, while Nvidia rose 0.7%.
Nvidia’s move followed a record $150 billion increase to its share buyback authorisation, announced on Monday by the world’s most valuable company.
Anthropic was also in focus after its initial public offering prospectus showed sharp growth over the past year, alongside widening losses. The artificial intelligence company is targeting a valuation of more than $2 trillion, which could provide a benchmark for how leading AI businesses are valued on Wall Street.
The AI theme has powered much of the market’s rise since October 2022. Investors were also awaiting remarks from OpenAI chief executive Sam Altman at the company’s DevDay event later on Tuesday.
The S&P 500 suffered its biggest one-day percentage decline since late August on Monday, as technology shares came under pressure from geopolitical uncertainty. Oil prices rose for a second consecutive session, adding to concerns that higher energy costs could fuel inflation and prompt central banks to raise interest rates.
US President Donald Trump said he had offered Iran nothing to end the war, rejecting reports citing US officials who said he was prepared to ease sanctions and release frozen funds in exchange for concrete steps on Iran’s nuclear programme.
“The markets are waiting for a breakthrough, or at least clarity, regarding the war. That would support sentiment. But it’s unlikely to arrive any time soon,” said Kyle Rodda, senior financial market analyst at Capital.com.
The yield on the benchmark 10-year US Treasury bond remained close to its highest level since 2007, reflecting expectations of tighter monetary policy. Traders currently see a 70% chance of another interest rate increase in October, according to the CME FedWatch Tool.
Markets are due to receive a reading on job openings for August later on Tuesday, with further economic data scheduled throughout the week. At least six Federal Reserve officials, including New York Fed president John Williams, are also due to speak.
Among individual stocks, Summit Therapeutics surged 22.4% after saying AstraZeneca would invest $2 billion in the company and work with it on a series of studies testing their cancer treatments. PepsiCo fell 0.7% after JP Morgan downgraded the drinks and snacks group to “neutral” from “overweight”.
