
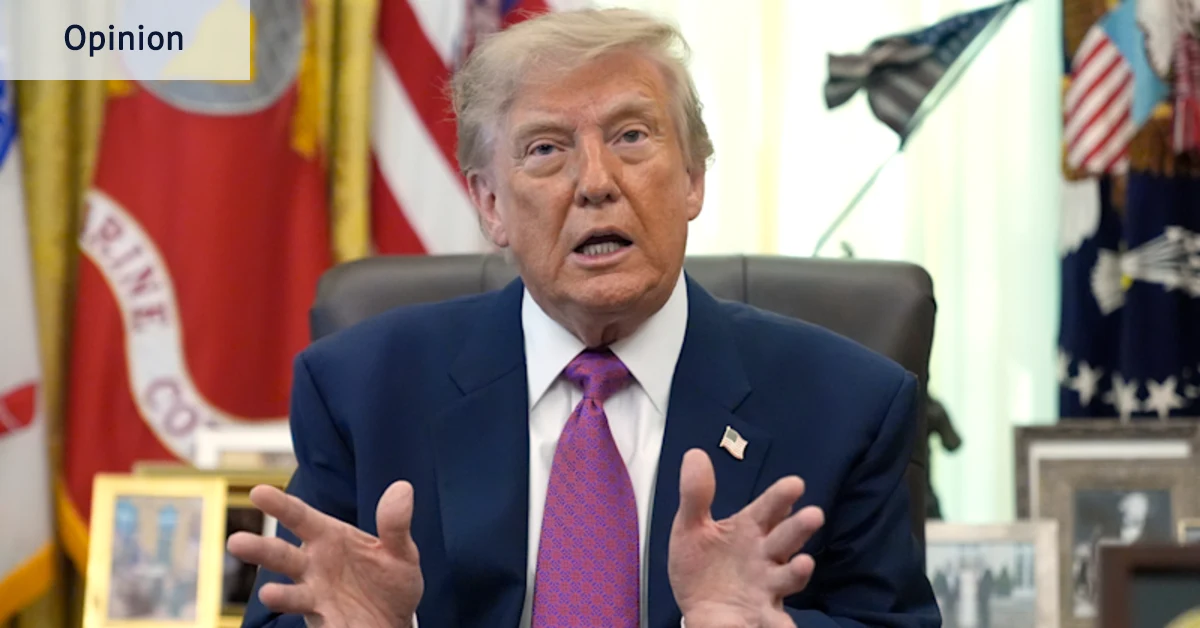
Donald Trump has pressured the G7 into releasing up to 100 million barrels of oil and diesel from emergency reserves in an attempt to bring down US fuel prices before next month’s midterm elections.
The four-month release includes a substantial, “front-loaded” drawdown of diesel stocks over the next 20 days. Oil prices initially fell below US$100 a barrel after the announcement, but later rebounded to more than US$102.
Petrol and diesel prices in the US have edged lower, although petrol remains about 40 per cent more expensive than at the same time last year and diesel is up by more than 70 per cent.
The agreement followed Mr Trump’s threat to ban US diesel exports, a move that would have placed further pressure on economies in the European Union and the UK, both of which rely heavily on American imports ahead of winter.
Mr Trump has since said the export ban was never going to happen. US oil companies had warned that, while such a measure might provide brief relief, it would eventually force domestic refiners and producers to cut output of petrol, diesel and jet fuel as inventories accumulated.
The limits of the G7 oil reserves release
The G7 release is expected to add less than 1 million barrels a day to global supply for four months. The split between crude oil and diesel has not been detailed, but the industry view is that roughly 50 million barrels of each will be released.
That extra supply comes as the global energy market faces a much larger shortfall. Refinery output worldwide is about 7 million barrels a day below last year’s level, while oil inventories are at their lowest point for five years.
The disruption has been compounded by the conflict in the Middle East. Refineries have been damaged, the flow of oil through the Strait of Hormuz has been reduced by attacks on tankers, and Russia has restricted diesel exports after strikes on its refining infrastructure.
China has also halted refined-product exports again, having been shipping about 1 million barrels a day before the war. Refineries outside the conflict zone, particularly in the US, are already operating at about 95 per cent of capacity and have little scope to increase production significantly.
US diesel inventories are at their lowest seasonal level since records began in 1982. Although American refineries are benefiting from exceptionally high margins, their stocks of refined products have also been run down.
The reopening of the Strait of Hormuz has failed to restore normal conditions. Tanker rates, which ranged from about US$30,000 to more than US$100,000 a day before the war, have risen above US$800,000. Insurance for larger vessels can cost as much as US$10 million, compared with about US$250,000 previously, where cover is available at all.
Those higher transport and insurance costs are feeding into fuel prices. They are likely to remain in place until hostilities end and shipping through the strait returns to something close to its pre-war norms.
Damage to Middle Eastern refineries will also take months, or potentially years, to repair. Saudi Arabia, once the world’s second-largest producer of diesel, is now producing less than 60 per cent of its pre-war refined-product volumes.
Russia has banned diesel exports until at least the end of this month, and the restriction could last longer as Ukraine threatens to intensify attacks on its refining infrastructure. The resulting pressure on refined products may therefore worsen despite the emergency stock release.
A survey of US oil and gas executives by the Federal Reserve Bank of Dallas found that 48 per cent expected diesel prices to take more than a year to return to last year’s levels.
The consequences extend beyond the petrol pump. Diesel is used by lorries, freight trains, ships, tractors and construction machinery, meaning higher prices are feeding into the cost of goods. US farmers are also facing increased fertiliser costs because the Middle East has been a major producer.
The resulting pressure on household and business budgets is adding to inflation and risks weakening economic activity, creating the prospect of stagflation. Republicans are already concerned about the impact of rising living costs on next month’s elections.
The G7 oil reserves release may temporarily narrow the gap between supply and demand, but it also reduces the emergency buffers available to respond to another shock. With the conflicts in the Middle East and Ukraine continuing, the measure is unlikely to reverse the wider forces keeping petrol and diesel prices high.
That leaves Mr Trump’s intervention with limited time to influence voters. Even if the release brings short-term relief, the underlying supply shortage and the continuing impact of the Middle East war on US fuel prices are likely to persist through the second half of his term.
