
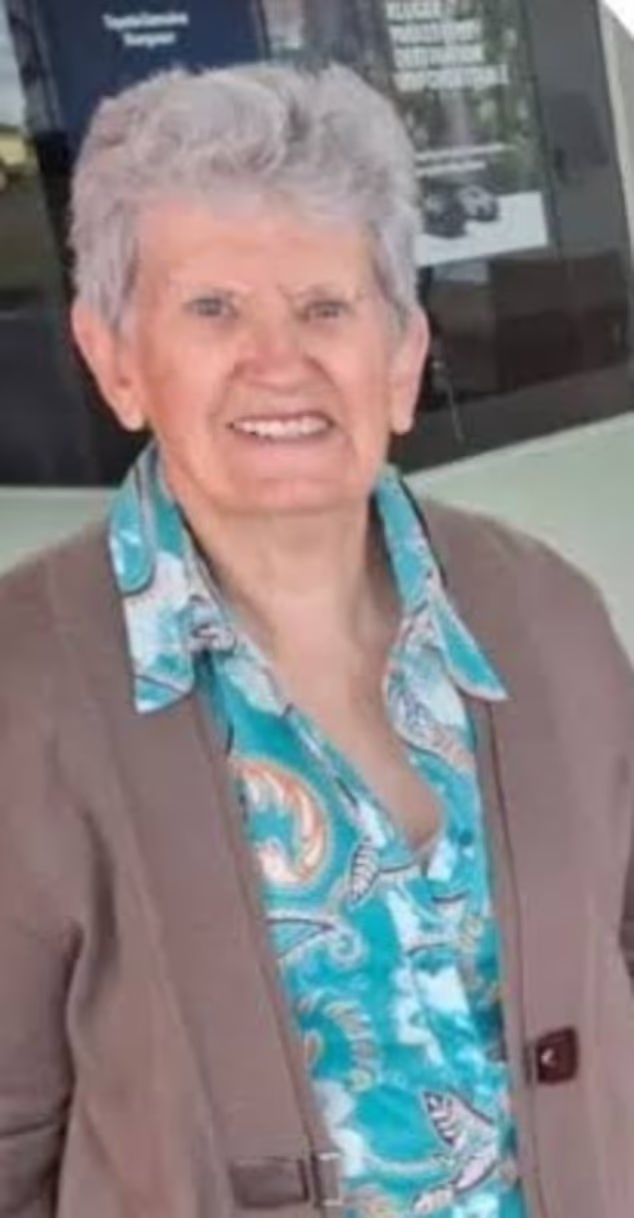
A Canberra retiree has told young Australians to give up luxuries such as clubbing if they want to buy a home, as Australian interest rates are expected to rise again and make home ownership even harder to achieve.
Anne Meade, 79, said her generation had saved carefully and paid off their homes without financial help from their parents. The former Commonwealth public servant said younger people should live within their means rather than borrow for non-essential spending.
“If you couldn’t afford something, well, you didn’t go out and buy it and be paying it off with a huge interest. You waited until you had money,” she said.
“You didn’t go out and go clubbing and that sort of thing.”
Her comments came ahead of an expected Reserve Bank of Australia decision on Melbourne Cup Day. The central bank is tipped to raise its cash rate for the fifth time in 2026, taking it to 4.85 per cent – its highest level in 18 years.
The expected increase comes despite Australian property prices falling for a seventh consecutive month, according to the material.
Ms Meade bought her unit in 1989 on what she described as a modest income, when interest rates were approaching a record 17.5 per cent. She said values instilled by her parents had taught her to be careful with money and to cut back on non-essential purchases.
“I was used to being careful, not frugal, but careful with my money,” she said.
She acknowledged that not having children had also helped her finances.
Young Australians facing larger mortgage debts
Real estate agent Tom Panos rejected comparisons suggesting borrowers today have an easier time than those who faced interest rates of 17.5 per cent in the early 1990s.
He said mortgage repayments now took up a much larger share of household income because property prices had risen sharply relative to earnings. Families were also dealing with higher costs for essentials including petrol, groceries, electricity and school fees.
“A guy said to me yesterday, ‘Tom we had 17.5 per cent interest rates, what are these people going on about?’” he said.
Mr Panos recalled the forced sales, mortgagee sales and pressure on families and businesses during the early 1990s. But he said the scale of modern mortgage debt meant today’s borrowers were carrying a different burden.
“But I can tell you what I’m seeing families carrying today, and I can tell you it’s harder than what people think,” he said.
He said a lower interest rate could still be more painful when applied to a much larger loan, adding: “4.6 per cent on a giant mortgage is more painful.”
In 1990, Sydney’s median house price was about $187,000. With a 20 per cent deposit, a buyer would have needed a mortgage of about $150,000; even at interest rates of around 17 per cent, the annual interest bill would have been roughly $25,000.
Today, the median Sydney house price is described as about $1.7 million. An 80 per cent mortgage would be around $1.36 million, with interest at about 6.4 per cent costing approximately $87,000 a year.
Australian households owed the equivalent of 178 per cent of their annual disposable income in June 2026, among the highest levels recorded since figures began in 1977.
“There’s no breathing room and unlike the late 80s and 90s, which was a sharp, brutal period, households today have been carrying this pressure for a few years,” Mr Panos said.
He added that the issue was not a competition over which generation had suffered more, but recognition that modern borrowers were taking on substantially larger debts.
“The mortgage is so much bigger, and that’s why the pain is so much deeper,” he said.
