
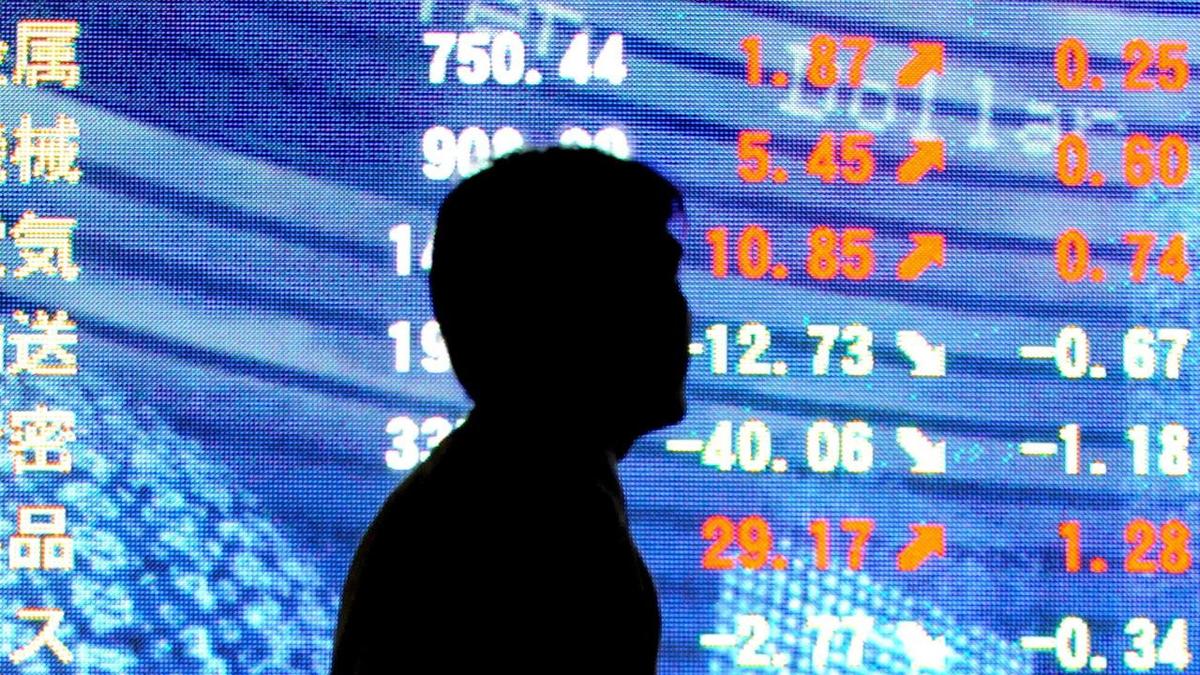
Asian share markets moved higher as strong demand linked to artificial intelligence supported chipmakers, while oil prices eased on expectations that Saudi Arabia could restore supplies after a reported Houthi attack on Riyadh.
South Korea’s tech-heavy index rose 1.1%, while MSCI’s broadest index of Asia-Pacific shares outside Japan gained 0.3%. Japan’s Nikkei was closed for a public holiday, although futures climbed 0.5%.
Trading was subdued during Japan’s Silver Week holiday, with the dollar little changed at 157.00 yen. Investors remained alert to the possibility of intervention by the Bank of Japan, after the yen strengthened on Friday following a reported rate check by Japanese authorities.
Futures pointed to further gains in the United States, with S&P 500 contracts up 0.3% and Nasdaq futures 0.4% higher. In Europe, EUROSTOXX 50 and DAX futures each rose 0.2%, while FTSE futures were flat.
Bond markets remained under pressure after a sharp sell-off pushed US two-year yields up 36 basis points over the past two weeks, to 4.7604% — their highest level since mid-2024.
Investors have increased their expectations of further interest rate rises after hawkish guidance from the Federal Reserve last week. Futures now imply a 56% chance of a rate increase in October, while a move by the end of the year is considered highly likely.
Analysts at BofA said: “Tightening cycles are generally front-loaded, and the Fed almost never stops after one hike.”
They added: “With nominal consumer spending up 6.3 per cent on the year, well above the 5 per cent level historically associated with above-target core inflation, the Fed has little choice but to restrain demand.”
The analysts said they were retaining their forecast for two further increases, in October and December. Central banks in the European Union, the UK, Japan, Australia and New Zealand are also expected to tighten policy again before the end of the year.
Oil prices slipped despite fresh threats exchanged by Iran and the United States and an attack by the Houthis on the Saudi capital. Brent crude fell 0.2% to US$103.68 a barrel, while US crude was down 0.3% at US$100.02.
Reports suggested Saudi Arabia was seeking to restart some flows quickly through its main east-to-west pipeline, which was damaged in attacks last week, although details remained limited.
Vivek Dhar, head of commodities at Commonwealth Bank of Australia, said: “The closure of the East-West pipeline has materially altered the state of the oil market.”
He said oil markets now had an estimated five to 10 weeks before global oil and refined product inventories were depleted, compared with forecasts of 15 to 20 weeks only a fortnight earlier.
Mr Dhar said the situation could increase pressure on Washington to reach an agreement with Iran, including to restore some flows through the Strait of Hormuz and keep the Bab el-Mandeb passage open.
In currency markets, the euro was steady at US$1.1477 after falling almost 1% last week as the dollar strengthened. French government debt also remained under scrutiny, with its risk premium reaching its widest level since the eurozone debt crisis on Friday.
German debt could come under renewed pressure after Chancellor Friedrich Merz’s mainstream conservative party recorded its worst election result since 1949.
Gold, which does not pay interest, was also weighed down by higher yields and fell 0.2% to US$4,370 an ounce.
