
Health insurance open enrollment for 2027 begins on November 1, giving millions of Americans who buy cover through HealthCare.gov or state-based marketplaces the chance to review their policies and compare alternatives.
People who want cover to begin on January 1 must generally enrol or change plans by December 15. The wider enrollment period runs until January 15, with later selections taking effect on February 1, although deadlines can vary between state marketplaces.
The period does not apply in the same way to everyone. Medicare has a separate enrollment window, running from October 15 to December 7, while employer-sponsored schemes commonly set their own deadlines during October and November.
Mychal Winter, president of the National Association of Benefits and Insurance Professionals, said consumers should examine more than the monthly premium before deciding whether to renew or switch plans.
Review your healthcare spending
Households should begin by looking back at their medical costs over the past year, including appointments, prescriptions, tests and hospital treatment.
That review can help identify likely needs for 2027. Someone who expects regular treatment or a costly procedure may benefit from a plan with higher monthly premiums but lower costs when care is used.
Consumers should also update their estimated income and household details when applying, as those figures can affect eligibility for premium tax credits and other financial assistance.
Compare premiums and overall plan costs
Premiums may have changed since the previous year, making it important not to assume that an existing policy remains the cheapest option.
Winter said rising healthcare, labour and provider costs could push premiums higher, and advised households to consider whether their current plan still fits their budget while meeting their medical needs.
The lowest monthly premium is not necessarily the least expensive policy overall. Deductibles, co-payments, coinsurance and the annual out-of-pocket maximum can all have a significant effect on the final cost.
Check that your doctors remain in network
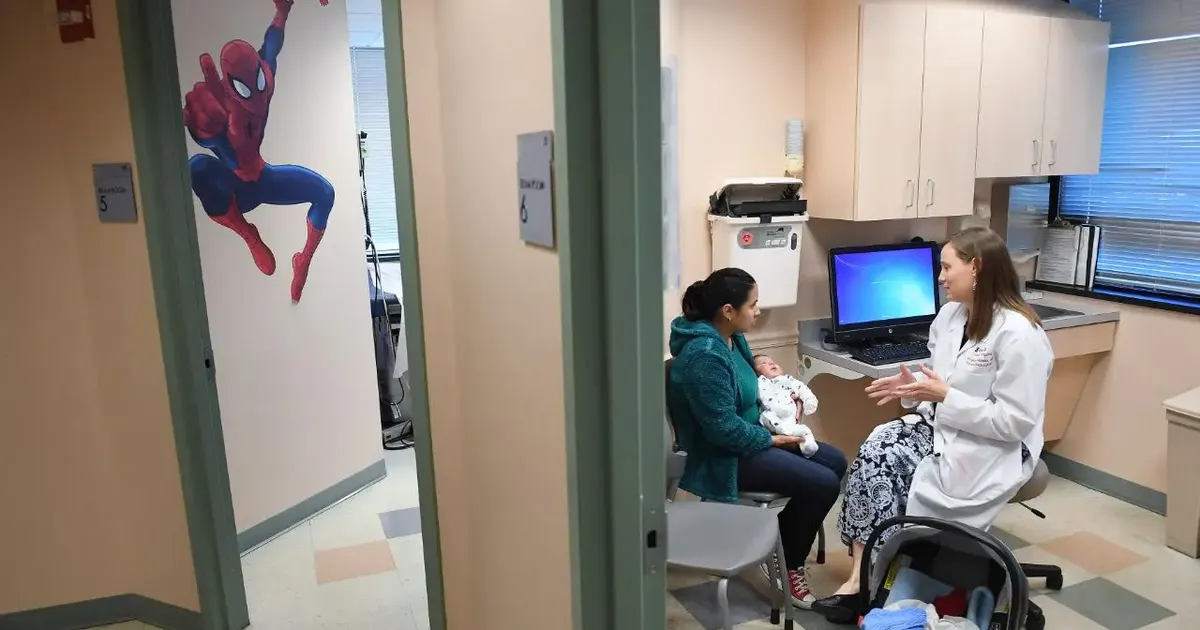
Insurance companies and healthcare providers can change their contractual arrangements from one year to the next. As a result, a doctor or hospital used regularly may no longer be covered at the preferred rate.
Consumers should check the insurer’s latest provider directory and confirm directly with their primary care doctor, specialists and preferred hospitals before enrolling.
A preferred provider organisation, or PPO, can offer greater flexibility when choosing doctors and specialists, sometimes without a referral. However, using out-of-network providers can result in substantially higher bills.
Balance deductibles against monthly premiums
High-deductible plans can reduce monthly payments, but they require policyholders to pay more themselves before insurance begins covering many services.
That approach may work for people with limited medical needs and enough savings to cover an unexpected bill. Others could face financial difficulty if they suddenly need treatment and cannot afford the deductible.
Consumers should compare the deductible with the plan’s out-of-pocket limit, as well as the cost of primary care visits, specialist appointments, emergency treatment and hospital stays.
Look at health savings account options
Some eligible high-deductible plans are paired with a health savings account, or HSA, which can be used to pay for qualifying medical expenses.
Contributions can receive favourable tax treatment, and unused balances generally roll over from year to year rather than expiring. The money may also be used towards a deductible and other eligible healthcare costs.
Before choosing a plan, households should check whether it qualifies for an HSA and consider whether they can afford to contribute regularly while still keeping enough money available for immediate medical expenses.
