
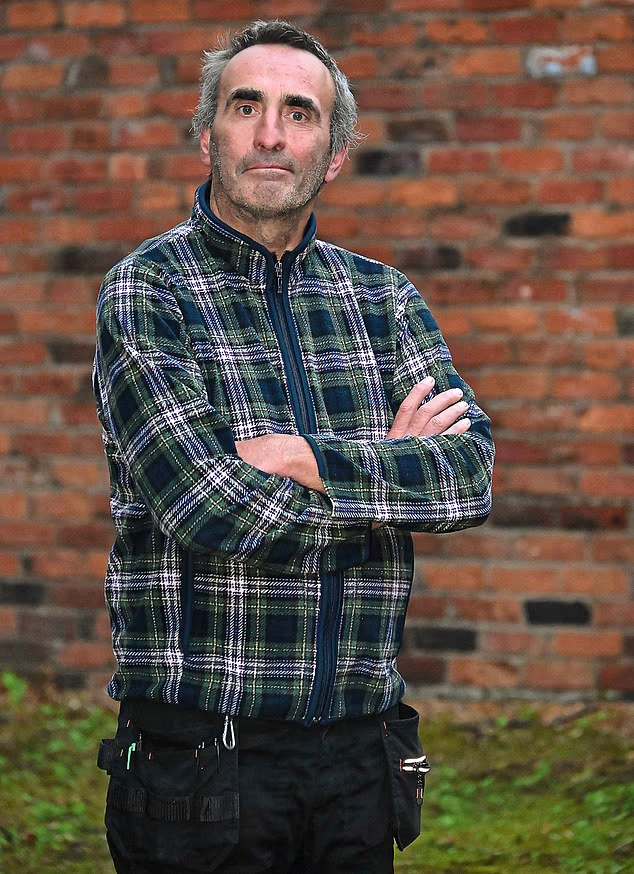
Late-bloomer pension savers are being urged to act before retirement, after research suggested they could be £73,000 worse off than people who plan from the outset. David Gate, from the North West, began taking his pension seriously at 50 after years of prioritising work, a mortgage and other financial commitments.
Mr Gate had little in retirement savings when he reached that age. Earlier in his career, he had declined to join a pension scheme at a technology company after colleagues told him it was poorly managed, while a plan to start a personal pension was abandoned in favour of saving for a home.
His parents’ retirement brought home the consequences of delaying. Both had enjoyed comfortable later lives supported by workplace and state pensions after careers as a town planner and primary school teacher.
“They lived quite comfortably on their workplace and state pensions,” Mr Gate said. “My dad was pretty much able to do what he wanted.”
Standard Life estimates that one in four workers are “late bloomers” – people who were previously disengaged from retirement saving but have begun planning more seriously. It also identifies “planners”, who take an organised approach, and “wingers”, who adopt a largely hands-off attitude.
Its figures suggest a worker paying the minimum five per cent of salary, alongside a three per cent employer contribution, from the age of 22 to 50 and then increasing payments to seven per cent could build a pension pot of £274,000 by 68.
By comparison, someone paying eight per cent of their salary from the start could have £347,000. Those who continue to take little interest in their pension could have £252,000, according to the figures.
Emma Furlonger, of Standard Life, said late starters should not assume they had lost their opportunity to prepare for retirement.
“If you’re a late bloomer, the message isn’t that you’ve missed the boat,” she said. “Everyone’s journey to retirement is different, but starting to pay attention today can still make a meaningful difference.”
How late pension savers can make up ground
Mr Gate joined a defined benefit pension scheme when he was 50, while working first as a technical demonstrator and later as a teacher at a college. He paid into the scheme for five years before returning to technical work in the entertainment industry.
A defined benefit pension provides a guaranteed annual income that rises with inflation. After leaving the college, he began paying into a personal pension and later joined an employer’s defined contribution scheme at a production company.
Under automatic enrolment rules, eligible employees must pay at least five per cent of salary into a workplace pension, while employers contribute a minimum of three per cent. Mr Gate also pays 10 per cent of his freelance earnings into his private pension.
Now 62, he has £90,000 in his defined contribution pension and expects to receive about £4,000 a year from the final salary scheme linked to his time in education. He will also qualify for the state pension at 67.
Mr Gate has paid off the mortgage on his two-bedroom terrace home and does not expect to retire immediately. He believes he may continue working until between 70 and 75 to build up further savings.
He is planning for a modest retirement rather than expensive holidays or cruises, focusing instead on covering his bills and keeping occupied with hobbies such as making music and reading.
“It’s not too late. You must put in what you can,” he said.
Ways to boost a pension later in life
Workers should check whether their employer will match increased contributions. Some schemes will match an employee paying six per cent, for example, resulting in a combined 12 per cent of salary being paid into the pension.
Contributions should also be reviewed after major changes in circumstances. A pay rise or children moving out could free up money to redirect into retirement savings, while increasing payments immediately after a salary rise can prevent the extra income being absorbed into day-to-day spending.
Tax relief can also increase the value of pension payments. A basic-rate taxpayer paying £80 can contribute £100, while higher-rate taxpayers need to pay £60 and additional-rate taxpayers £55 to achieve the same contribution, subject to the relevant pension arrangements.
Higher- and additional-rate taxpayers using a relief-at-source scheme may need to claim their extra tax relief from HM Revenue and Customs. Basic-rate relief is added automatically in that system.
Checking a pension provider’s app can help savers see their contributions building, although investments should not be monitored too frequently because markets rise and fall over time.
Those intending to work beyond 65 may also need to check when their pension is due to move into lower-risk investments. Schemes can begin shifting money from shares into bonds and cash between five and 15 years before the target retirement age, which may be earlier than necessary for someone planning to work longer.
Late starters should also check their state pension position. Most people need 35 years of National Insurance contributions to qualify for the full amount, while missing years may be filled by making additional contributions if they are eligible.
