
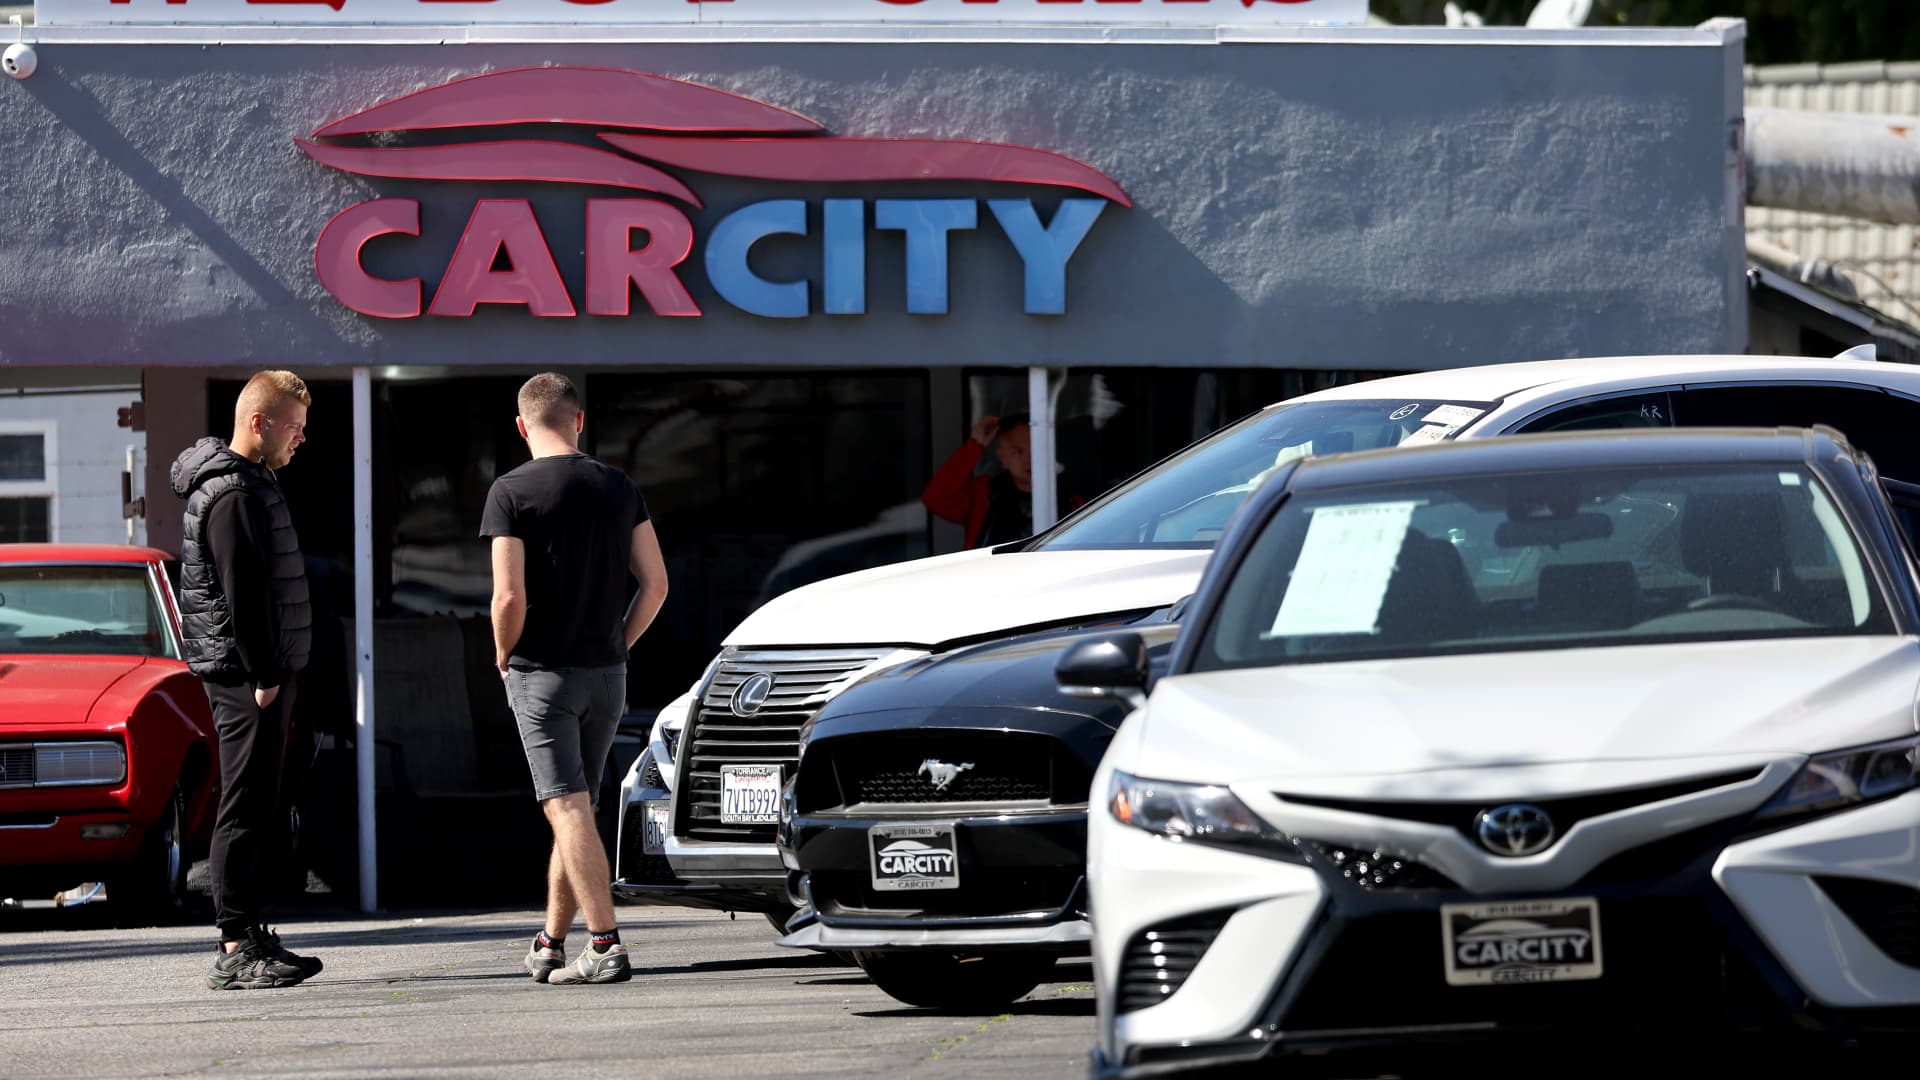
Used vehicle prices in the US are forecast to rise only 0.2% this year, sharply below the previous estimate of 2%, as higher fuel costs and wider inflationary pressures squeeze household budgets.
Cox Automotive revised down its outlook for the Manheim Used Vehicle Value Index after the benchmark fell 0.6% in September. It was the first month since early last year in which the index was not higher than it had been a year earlier.
Wholesale used-vehicle prices, excluding seasonal adjustments, dropped 1.2% year on year in September and 1.3% from August, with depreciation accelerating during the third quarter.
The Manheim index tracks vehicles sold through US wholesale auctions and is closely watched because retail prices typically follow movements in wholesale costs.
Jeremy Robb, chief economist at Cox Automotive, said the market had initially held up despite higher fuel prices, but conditions had since deteriorated.
“The first half of the year actually showed more appreciation than usual, even in the face of higher fuel prices. But with the conflict in the Middle East ongoing, diesel prices at record highs, and interest rates climbing rapidly, increasingly worrying both businesses and consumers, wholesale prices have felt the sting,” he said.
Average petrol prices in the US reached $4.33 a gallon in September, according to AAA, exceeding the previous September record of $3.83 set in 2023. Smaller, more fuel-efficient cars increased in value during the quarter, while large trucks and SUVs performed poorly.
Cox Automotive also said electric vehicle sales and the number of vehicles returning from leases continued to grow, adding to changes in the used-car market.
Retail demand remains relatively healthy, but Cox said the shift in wholesale values suggested dealers had reached a limit on what they could charge consumers.
The average listed price of a used vehicle was $27,239 in August, compared with more than $50,000 for a new vehicle. Most US consumers buy used vehicles because they are more affordable than new models.
