
Apollo chief economist Torsten Slok has warned that the AI boom may be built on an economic weakness: the cost of producing computing power could be greater than the value it creates for users.
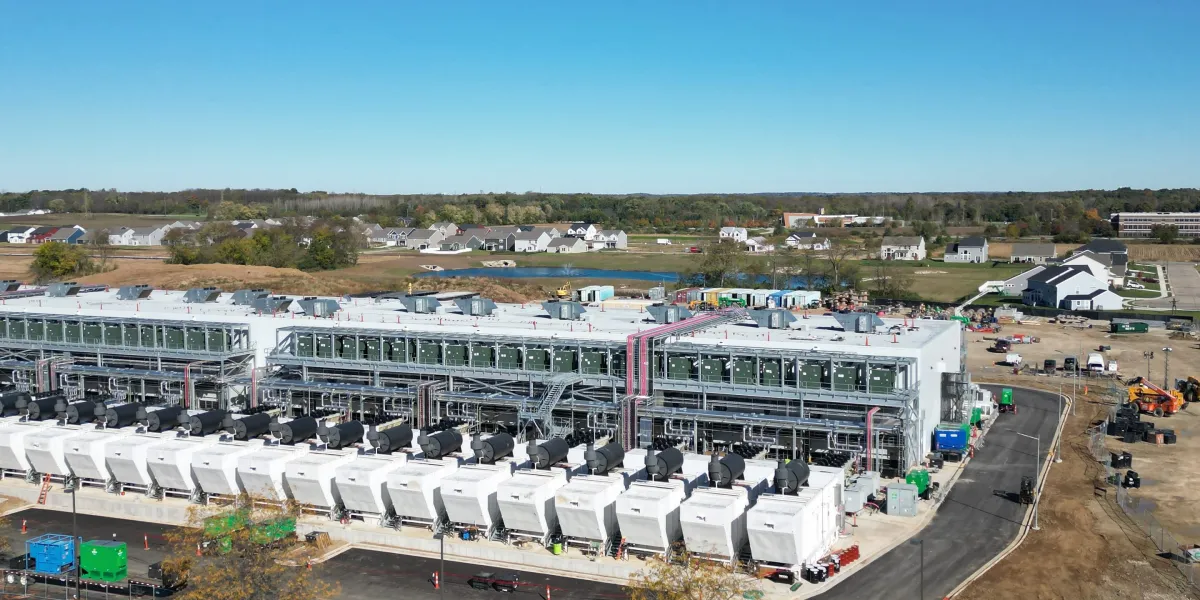
His comments came as AI-related shares, particularly chipmakers, fell amid growing doubts over how long the sector’s enormous capital spending can continue. A group of major technology companies is expected to spend about $800 billion this year, with expenditure forecast to exceed $1 trillion next year.
Slok said the recent slowdown in token spending growth suggested demand for computing power was flat and highly responsive to price. Most companies investing in AI had yet to record meaningful productivity gains, he added, making the technology appear more like a cost than a source of growth.
“The core economic flaw in the AI bull case is that the marginal cost of producing compute exceeds the marginal benefit it delivers to users, raising questions about claims of unlimited demand for data centers,” he said.
In his assessment, the key factor in plans to build data centres was not the amount of physical capacity or available power, but the price customers were prepared to pay for computing power. Businesses would only accept high prices if the technology delivered faster revenue growth, increased profits or substantial savings.
“Maybe that will come in the future. Maybe not,” he warned.
Concerns over AI financing
Slok also raised concerns about circular spending within the AI industry. AI companies have faced scrutiny over arrangements in which they provide funding or guarantee debt for other businesses that are also major customers.
He suggested a comparable relationship existed between AI start-ups and the venture capital firms backing them. Slok said 80% of the top 1% of AI spenders were venture capital-backed, arguing that some start-ups were paying their computing bills with investment capital rather than organically generated earnings.
He later said AI had “delivered zero financial payoff” to US companies outside the large technology platforms. While profit margins and revenue per worker were increasing among the so-called Magnificent Seven, he said the rest of the S&P 500 had not seen the same improvement.
Slok argued that many mainstream companies neither needed the latest AI model nor wanted to pay for it. He said the technology might become cheaper and more widely available without necessarily improving companies’ financial results.
“AI may be a great calculator, but in business, intelligence is mostly judgment,” he wrote. “Judgment depends on context, and the answer varies with which human or which model you ask.”
He added that AI did not understand “accountability, trust, culture, unwritten rules, ethical trade-offs or fairness”, which he said could shape reputational risk and ultimately affect revenue and profit margins.
Debt risks spread across the sector
The financing concerns have extended beyond the biggest technology companies. Meta, which plans to spend between $135 billion and $145 billion this year, has already issued substantial debt and announced a new class of shares, partly to help chief executive Mark Zuckerberg pay for a possible wealth tax in California.
The cost of insuring Meta’s debt against default reached a record on Thursday. Five-year credit default swaps widened by 7.6 basis points to an all-time high of 114.79 basis points.
Smaller AI infrastructure companies have also come under pressure. CoreWeave’s shares have fallen by more than 30% this month, while its five-year credit default swaps have risen to 1,145 basis points.
Mark Habib, S&P’s global head for digital infrastructure, has highlighted what he described as “interconnected financing structures” linking major technology companies with data-centre projects and smaller AI businesses.
“It is safe to assume that there is more (debt) out there that we are not seeing,” he said during a roundtable in London.
Habib said liabilities might not be visible if they were not disclosed by the major technology companies or involved transactions that were not rated by S&P.
